
Your full monthly mortgage payment — principal, interest, taxes, insurance, PMI, and HOA in one PITI total. Enter the home price, down payment, rate, and term, then add the annual property tax, homeowners insurance, PMI, and monthly HOA dues, and the calculator shows the payment you will actually make each month.
It runs entirely in your browser with no sign-up. A principal-and-interest quote makes every home look cheaper than it is; the escrow parts are the surprise at closing. For the principal-and-interest piece alone, see the Home Loan Calculator, and for the yearly interest split, the Loan EMI Calculator.
How to use
- Enter the home price and your down payment — the loan amount is figured for you.
- Enter the annual interest rate and the loan term in years.
- Add the annual property tax, homeowners insurance, PMI if any, and monthly HOA dues.
- Read the total monthly PITI, the breakdown of each part, and the total interest.
Why use Toolsvine
A P&I-only quote makes every home look cheaper than it is, and the surprise arrives at closing when escrow is added. Toolsvine shows the tax, insurance, PMI, and HOA parts line by line next to principal and interest, with the formula visible — so you compare houses on the payment you will make, not the payment the listing advertises.
What is PITI, and how is it calculated?
PITI is the full monthly mortgage payment: principal and interest, property tax, homeowners insurance, and — where they apply — private mortgage insurance (PMI) and homeowners association (HOA) dues. The principal and interest come from the standard EMI formula on the loan amount, which is the home price minus the down payment; the tax and insurance are their annual figures divided by 12, and the HOA dues are already monthly.
The lender usually collects the tax and insurance into an escrow account and pays them for you, which is why the PITI total is the number that matters for your budget. PMI applies when the down payment is under 20% of the price, and the tool warns you when your down payment is below 20% and no PMI figure was entered — a common way buyers understate their real payment.
Worked example
Jordan buys a $425,000 home in Austin, TX with an $85,000 down payment (20%), leaving a $340,000 loan at 6.25% for 30 years. The principal and interest is $2,093.44 a month. Property tax of $5,100 a year adds $425.00, homeowners insurance of $1,800 a year adds $150.00, PMI is $0.00 at 20% down, and HOA dues are $50.00 — for a total PITI of $2,718.44 a month. The principal and interest alone would be $625.00 short of the real payment.
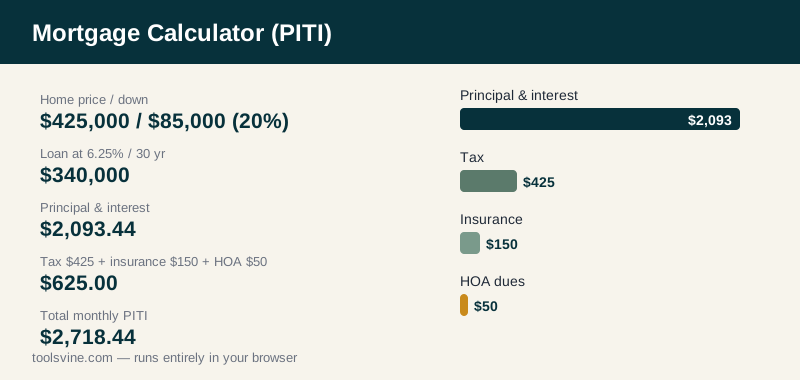
What each part of the payment costs
| Part | Monthly amount | Notes |
|---|---|---|
| Principal & interest | $2,093.44 | Fixed for the life of the loan |
| Property tax | $425.00 | $5,100 a year, can rise |
| Insurance | $150.00 | $1,800 a year, can rise |
| PMI | $0.00 | None at 20% down |
| HOA dues | $50.00 | Monthly, set by the association |
| Total PITI | $2,718.44 | The payment you budget for |
Over 30 years the principal and interest alone totals $753,638.40 — $413,638.40 of it interest on a $340,000 loan. Tax and insurance are not interest, but they are part of the monthly obligation, and both can rise: a tax reassessment or an insurance renewal can move the PITI by $100 or more with no change to the loan itself.
How do I lower my monthly PITI payment?
The biggest lever is the down payment: reaching 20% removes PMI entirely and shrinks the loan, which lowers the principal and interest at the same time. In the example, a 10% down payment instead of 20% raises the loan to $382,500, the principal and interest to $2,355.12, and adds $170.00 of PMI — a total of $3,150.12 a month, or $431.68 more for the same house.
The second lever is the rate: half a point on a $340,000 loan moves the payment by roughly $100 a month, so shopping lenders matters. The third is the home itself — property tax rates and HOA dues vary widely between neighborhoods, so two $425,000 homes can have PITI payments hundreds of dollars apart. Compare homes on the full PITI, never on the principal and interest alone.
Frequently asked questions
What does PITI stand for?
PITI stands for principal, interest, taxes, and insurance, and the acronym is often extended to include PMI and HOA dues. It is the full monthly mortgage payment: the loan payment plus the property tax, homeowners insurance, PMI, and HOA amounts the lender collects or that you owe. The PITI is the payment you budget for.
How much is the monthly payment on a $425,000 home?
With 20% down, a $340,000 loan at 6.25% for 30 years costs $2,718.44 a month in total PITI: $2,093.44 principal and interest, $425.00 tax, $150.00 insurance, and $50.00 HOA dues. With only 10% down the same home costs $3,150.12 a month, including $170.00 of PMI.
When can I stop paying PMI?
Usually once your loan balance falls to 80% of the home's original value — by paying the loan down, by the home gaining value, or by refinancing. PMI applies when the down payment is under 20% of the price. In the worked example, 20% down means no PMI at all, which saves $170.00 a month compared with a 10% down payment.
Does property tax stay the same over the loan?
No. Property tax is set by the county and school district and usually rises over time as home values and tax rates change, and homeowners insurance premiums rise too. The principal and interest part of a fixed-rate mortgage never changes, but the tax and insurance parts can move the PITI by $100 or more a month over the years.
What is the difference between PITI and P&I?
P&I is only principal and interest — the loan payment itself. PITI adds property tax, homeowners insurance, and, where they apply, PMI and HOA dues. In the worked example the P&I is $2,093.44 but the PITI is $2,718.44, so quoting P&I alone understates the real monthly cost by $625.00.
Is my mortgage information uploaded anywhere?
No. The home price, down payment, rate, term, tax, insurance, PMI, and HOA figures are processed in your browser and never leave your device. Nothing is uploaded, stored, or shared, and there is no account or sign-up. Estimates for planning only — not tax advice.