
How much will a home loan cost every month — and how much interest will you pay in total? This home loan calculator uses the standard EMI formula to give the monthly payment, total interest, and total payment for any loan amount, rate, and tenure in years, so the full price of the house is visible before you sign.
It runs entirely in your browser with no sign-up. For the complete monthly payment including taxes and insurance, try the Mortgage Calculator (PITI); for a month-by-month breakdown of every payment, the Loan EMI Calculator shows the yearly interest versus principal split.
How to use
- Enter the home loan amount.
- Enter the annual interest rate.
- Enter the tenure in years.
- Read the monthly EMI instantly, with total interest and total payment below.
- Open “Show steps” to see the EMI formula worked out.
Why use Toolsvine
A home is the biggest loan most people ever take, and the monthly payment is only half the story — the total interest over thirty years can exceed the loan itself. This tool shows both numbers together, using the rounded EMI × tenure convention lenders quote, so the cost is visible before you sign and before the rate lock expires.
How does a home loan payment work?
A home loan is repaid in equal monthly installments — EMIs — that cover both interest and principal. The EMI formula is E = P × r × (1 + r)n ÷ ((1 + r)n − 1), where P is the loan amount, r is the monthly interest rate (annual rate ÷ 12 ÷ 100), and n is the number of monthly payments. Early payments are mostly interest; the principal share grows as the balance falls, so the first years barely dent what you owe.
The totals here use the rounded EMI × tenure, the way lenders quote it. That matters because a payment rounded to cents, multiplied by 360 months, is the number your lender will actually collect — not the unrounded formula value. A small rate difference matters enormously over 30 years: on a large home loan, half a percentage point can be worth tens of thousands of dollars in interest.
Worked example
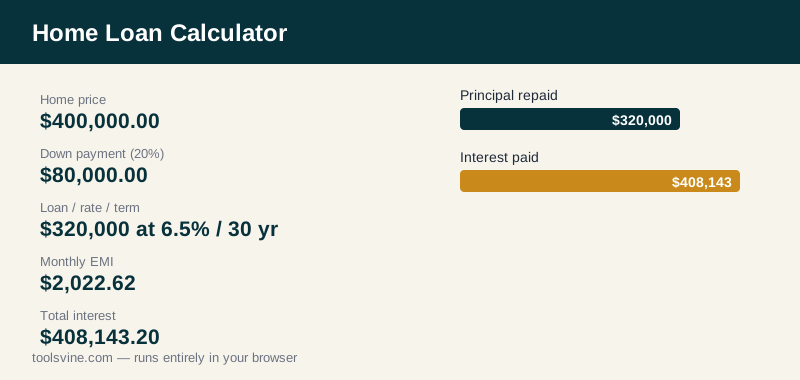
Alex and Jordan buy a $400,000 home in Austin, TX with a 20% down payment of $80,000, leaving a $320,000 loan at 6.5% for 30 years (360 months). The monthly rate is 6.5 ÷ 12 ÷ 100 = 0.005417, and the EMI is $2,022.62 a month. Over 30 years they pay $728,143.20 in total — $320,000 of principal plus $408,143.20 of interest, which is more than the loan itself.
Same $320,000 loan at different rates
| Rate | Monthly EMI | Total interest |
|---|---|---|
| 6.0% | $1,918.56 | $370,681.60 |
| 6.5% | $2,022.62 | $408,143.20 |
| 7.0% | $2,128.97 | $446,429.20 |
Half a point — from 6.5% to 7.0% — adds $106.35 a month and $38,286.00 of interest over the life of the loan. That is why shopping three lenders instead of one often saves more than any other single move a buyer makes, and why locking a rate a quarter point lower is worth real effort.
What changes my monthly home loan payment?
Four things change the payment: the loan amount, the interest rate, the tenure, and any extra principal you pay. A bigger loan raises the payment proportionally, a higher rate raises it sharply, a longer tenure lowers the monthly figure while raising total interest, and an extra payment cuts the balance so every later month costs less interest.
The down payment is the lever most buyers control. On a $400,000 home, 20% down leaves a $320,000 loan; 10% down leaves $360,000 and usually adds private mortgage insurance on top. A bigger down payment lowers the payment twice — less principal and often no PMI — which is why saving longer before buying can beat buying sooner. Remember the EMI here is principal and interest only; taxes, insurance, and HOA dues are separate, and the PITI calculator adds them in.
Frequently asked questions
How much is the monthly payment on a $320,000 home loan?
At 6.5% over 30 years, a $320,000 home loan costs $2,022.62 a month in principal and interest, for a total of $728,143.20 — $408,143.20 of it interest. That payment excludes property tax, homeowners insurance, and HOA dues. Enter your own loan amount, rate, and tenure in the calculator above for your exact figure.
How much interest will I pay on a 30-year home loan?
Often more than the loan itself. On a $320,000 loan at 6.5% for 30 years, total interest is $408,143.20 — about 128% of the amount borrowed. A shorter term or a lower rate cuts that total sharply: the same loan at 6.0% costs $370,681.60 in interest, saving $37,461.60 over the life of the loan.
Is a 15-year or 30-year home loan better?
A 15-year loan costs much less interest but much more each month, while a 30-year loan is easier monthly and far more expensive overall. Choose the 15-year term only if the payment still leaves room for savings and emergencies. If the 15-year payment would strain your budget, the 30-year term with occasional extra principal payments is the safer middle path.
Does a bigger down payment really help?
Yes, twice over. A bigger down payment shrinks the loan, which lowers the monthly payment and the total interest, and reaching 20% down usually removes private mortgage insurance. On a $400,000 home, 20% down means a $320,000 loan instead of $360,000 at 10% down — a smaller payment and no PMI on top.
Why is my early balance barely falling?
Because early payments are mostly interest. Interest is charged on the balance still owed, so when the balance is highest the interest part of each payment is at its largest. The principal share grows month by month as the balance falls, which is why extra payments made early — when the balance is highest — save the most interest.
Is my home loan information uploaded anywhere?
No. The loan amount, rate, and tenure are processed in your browser and never leave your device. Nothing is uploaded, stored, or shared, and there is no account or sign-up. The calculation uses the standard reducing-balance formula and the rounded EMI × tenure totals that lenders quote.